Vietnamese
The Department of Taxation provides this guidance in Official Dispatch No. 7403/CT-TMDT on tax liabilities of individuals providing digital information content products and services and affiliate marketing services in e-commerce.
In Official Dispatch No. 7403/CT-TMDT, the Department of Taxation provides guidance on the application of a 5% personal income tax (PIT) rate to affiliate marketing activities on e-commerce platforms. This is a notable provision in Section 1 of the Official Dispatch. Specifically:
Regarding the personal income tax rate: pursuant to Clause 14, Article 3 of the Law on E-Commerce No. 122/2025/QH15, affiliate marketing services in e-commerce mean the advertising of goods and services through access links, referral codes or similar methods linked to an e-commerce platform. Accordingly, affiliate marketing activities on e-commerce platforms shall be subject to the tax rate applicable to the provision of digital information content products and services relating to entertainment, video games, digital films, digital photos, digital music and digital advertising, for which the personal income tax rate is 5% under Point dd, Clause 3, Article 7 of the Law on Personal Income Tax No. 109/2025/QH15.
According to Official Dispatch No. 7403/CT-TMDT, tax liabilities are determined primarily based on the nature of the income received by an individual. Where an individual receives income under a labor contract or collective bargaining agreement entered into with an income-paying organization or individual in accordance with the labor law, such income shall be determined as income from salaries and remunerations. Organizations and individuals paying income shall withhold, declare and pay PIT in accordance with regulations.
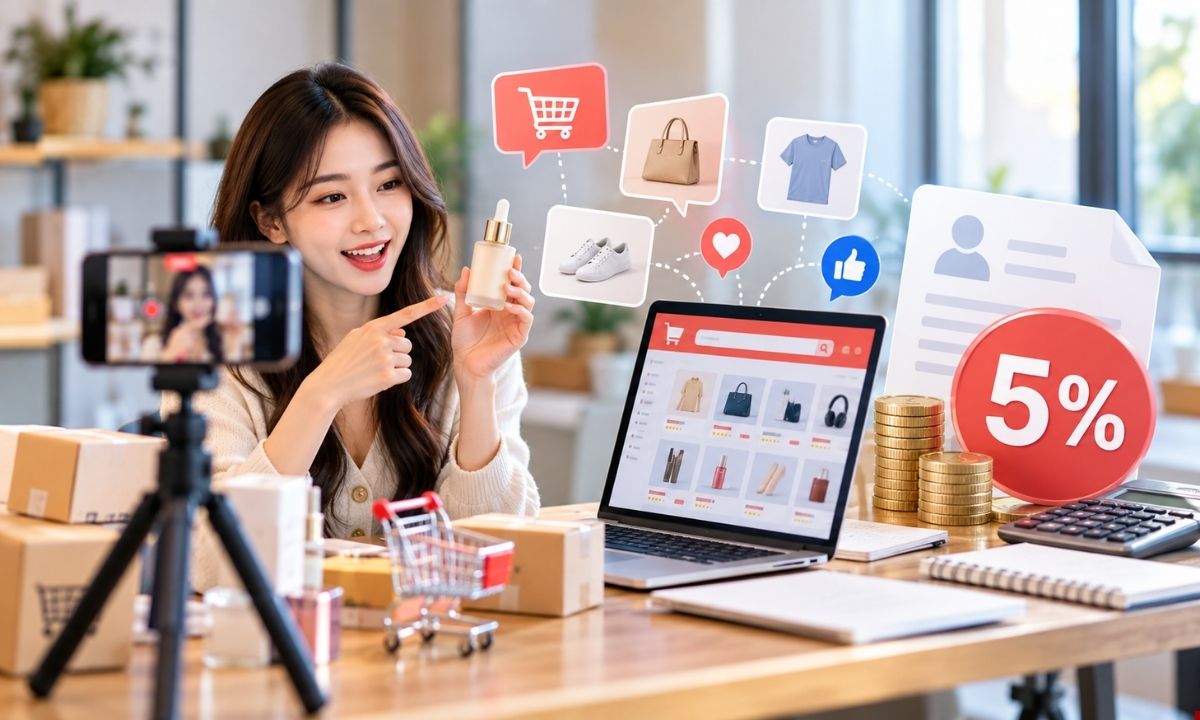
Where an individual engages in digital content creation, product promotion or affiliate marketing activities on e-commerce platforms or digital platforms and receives income from a platform or brand in connection with business activities, other than salary or wages, such income shall be determined as business income. Business households and business individuals shall make tax registration, declaration and payment in accordance with Decree No. 68/2026/ND-CP and Decree No. 141/2026/ND-CP.
Regarding the tax rate, the Official Dispatch specifies that affiliate marketing services in e-commerce mean the advertising of goods and services through access links, referral codes or similar methods linked to an e-commerce platform.
Accordingly, affiliate marketing activities on e-commerce platforms shall be subject to the tax rate applicable to the provision of digital information content products and services relating to entertainment, video games, digital films, digital photos, digital music and digital advertising. The PIT rate applicable to these activities is 5%, pursuant to Point dd, Clause 3, Article 7 of the 2025 Law on Personal Income Tax.